+91 945 889 6091
 infodesk@ibluu.com
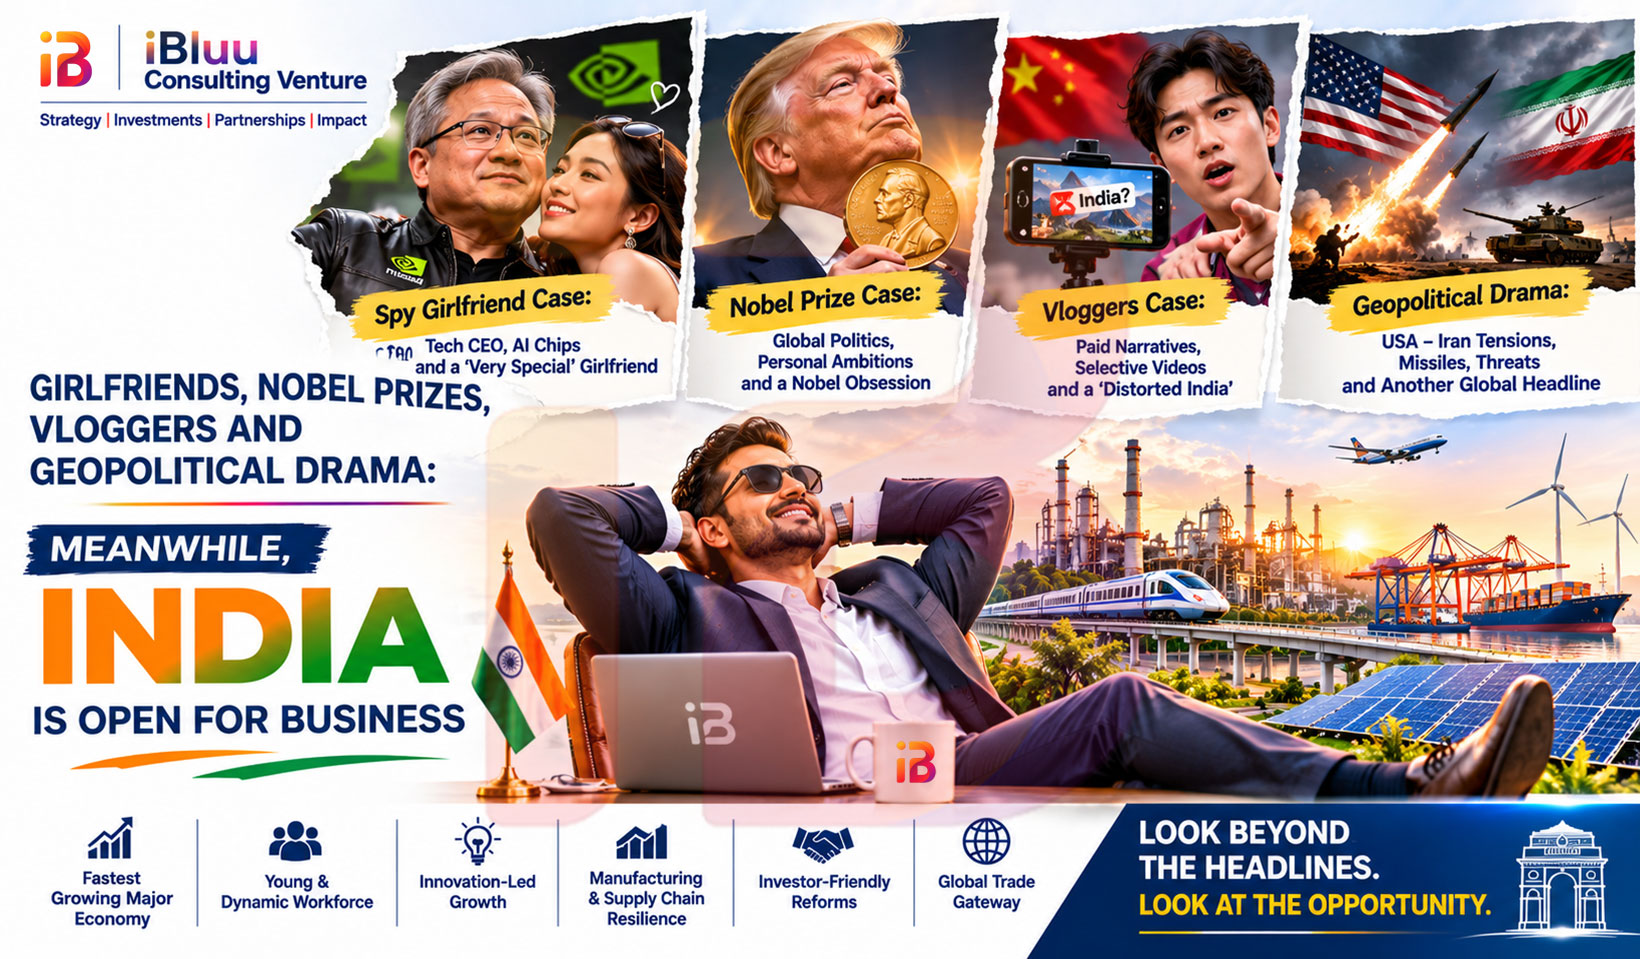
From International Spy-RomCom Dramas to Political Soap Operas About Awards and Power: The World Has Its Priorities. India Has Its Investment Opportunities.
A little international satire. A serious investment proposition. Why global capital should look beyond the world’s distractions and examine India’s expanding opportunities across healthcare, renewable energy, hospitality, startups, food businesses, retail and industrial development.
1. THE WORLD HAS DISCOVERED SOME VERY INTERESTING ALTERNATIVES TO ECONOMIC DEVELOPMENT
Before discussing India’s investment potential, let us acknowledge that the international business environment has become considerably more entertaining.
Who needs a conventional business conference when geopolitical relationship management can apparently provide an entire season of international intrigue? Somewhere, a conversation about technology, influence and strategic interests seems to have acquired the plot of a romantic thriller. Corporate networking may never look quite the same again.
Then there is the international awards industry. Some people dedicate their lives to scientific discoveries, humanitarian contributions and extraordinary intellectual achievements. Others appear to have developed an equally extraordinary interest in understanding why the world’s most prestigious recognition has not yet arrived at their doorstep. Perhaps the Nobel committee should consider introducing a category for Outstanding Achievement in Managing Expectations.
Tourism marketing, meanwhile, has entered an exciting new phase. A destination that has spent decades developing hotels, restaurants, transport networks and visitor experiences can apparently be assessed by a few dramatic videos, selective camera angles and an influencer with a particularly confident opinion. Millions of actual travellers may disagree, but fortunately, the internet has never required a majority vote before publishing a review.
And geopolitics? What a remarkable industry.
Somewhere, a protest becomes an international business strategy. Somewhere else, a political disagreement becomes a global economic forecast. Markets fluctuate, currencies react, diplomatic relationships change and suddenly millions of people become experts in international finance. A person who has never evaluated a project cash flow can confidently explain why an entire economy is finished.
Even investment decisions occasionally appear to follow an interesting philosophy: if the opportunity looks commercially questionable, perhaps a sufficiently attractive geopolitical narrative will improve the valuation.
It is an ambitious theory. Accountants, unfortunately, remain unconvinced.
And while the world continues to negotiate its relationships with awards, influencers, political egos, international controversies and occasional financial adventures, India is dealing with rather less glamorous responsibilities.
Hospitals need to be built. Medical colleges need qualified faculty. Solar projects need commissioning. Hotels need guests. Startups need customers. Local food brands need distribution. Manufacturing businesses need capital. Infrastructure needs financing. Investors need returns.
In other words, India has businesses to build.
The world may be competing for headlines. India is competing to create economic value.
The sarcasm is intentional. The investment proposition is not a joke.
A few reasons to consider India. Some serious. Some deliberately sarcastic.
Reason No. 1: When global markets become a roller coaster, India reminds investors that even financial panic occasionally needs a change of direction.
Global markets have become rather entertaining. One day, investors are celebrating. The next, they are checking geopolitical developments, central-bank statements and their portfolio valuations with the enthusiasm of someone reading an unexpected examination result.
Indian equities have experienced volatility, foreign selling and changing valuations. Yet the November 2026 reversal, with foreign portfolio investors returning strongly after months of outflows, demonstrates how quickly capital allocation can change when valuations, earnings and global risk preferences shift.
Apparently, even international capital sometimes needs a little time to think things over.
The lesson is not that India is always green when the rest of the world is red. We are not selling a permanent green traffic signal.
The lesson is that investors should distinguish temporary market sentiment from long-term economic fundamentals.
Markets may have mood swings. Investment decisions should not.
Reason No. 2: India offers business opportunities without requiring investors to acquire a second degree in international romance, intelligence affairs and geopolitical matchmaking.
Somewhere in the international news cycle, ordinary relationships have apparently become complicated enough to require the vocabulary of national security. What was once a matter of personal chemistry now sounds like a classified strategic partnership. One almost expects the next corporate networking event to include a background-verification exercise before exchanging business cards.
Meanwhile, India offers a rather more conventional way of building relationships: identify a credible partner, negotiate commercial terms, sign an agreement and deliver what was promised.
You can evaluate a hospital, finance a solar project, partner with a manufacturer or launch a consumer brand without first establishing whether the latest international relationship belongs in a romantic comedy, a diplomatic briefing or an intelligence documentary.
Your investment committee can discuss EBITDA, IRR, DSCR and market penetration.
It does not need a separate department for geopolitical matchmaking, relationship surveillance or interpreting every international plot twist.
In India, the relationship we recommend investors focus on is the one between capital, capability and commercial returns.
Reason No. 3: You can hire a market research team instead of allowing a viral video to become your country’s official tourism policy.
Tourism marketing has entered a fascinating new era. Apparently, years of hospitality infrastructure, thousands of hotels, millions of travellers and an entire tourism industry can occasionally be put on trial by a camera, a dramatic voice-over and a video that has discovered the extraordinary commercial value of outrage.
One carefully edited clip can apparently become a national tourism audit. A few selective experiences can be promoted as universal truths. And if the footage comes with sufficiently dramatic background music, who needs visitor statistics, customer surveys or destination benchmarking?
Of course, actual tourists, hospitality operators and destination managers may have some inconvenient data. But data does not always go viral. Drama, on the other hand, rarely struggles for distribution.
India’s consumer and tourism markets deserve to be understood through actual customer behaviour, purchasing power, regional preferences, visitor experience and commercial evidence—not through unverified online narratives.
In the age of viral misinformation, reliable market intelligence is an investment asset.
A destination should be judged by its performance, not by the production quality of its latest controversy.
Reason No. 4: India does not require you to win a global popularity contest before you can build a profitable business. Nor does your investment proposal need a Nobel Prize.
The international awards season is always interesting. Scientific discoveries take years. Research requires discipline. Innovation demands persistence. And recognition, naturally, is a matter for independent institutions.
Yet the global conversation occasionally makes it sound as though an award announcement is the most important economic event of the year. Somewhere between the nominations, expectations and disappointment, the actual business of building an economy can become a surprisingly neglected subject.
India’s investment proposition is refreshingly less complicated.
You do not need a Nobel Prize, a diplomatic standing ovation, a permanent seat at every international summit or a standing ovation from the global commentariat.
You need a credible product, a viable business model, competent execution, regulatory compliance and customers willing to pay.
Your hospital does not need an international peace award to treat patients. Your solar plant does not need a literature prize to generate electricity. Your hotel does not need a diplomatic endorsement to fill rooms.
A profitable business is not an award category. It is an operating achievement.
Reason No. 5: You can build a business without turning every political disagreement into an international protest festival.
The global economy has developed a curious relationship with public demonstrations. Somewhere, a political disagreement becomes a street spectacle. Somewhere else, a local issue acquires international sponsors, hashtags, microphones and a surprisingly ambitious global distribution strategy.
One almost wonders whether some protest organisers have started measuring campaign success in terms of social-media impressions rather than the actual resolution of the issue.
Of course, public protest, political disagreement and civic participation are legitimate features of democratic societies. India has its own political debates, public demonstrations, policy disagreements and regulatory challenges. Investors should neither ignore these realities nor confuse every demonstration with a threat to commercial activity.
The sensible approach is to examine the actual legal environment, institutional protections, contractual enforceability, regulatory framework and project-specific risks.
A hospital should be evaluated on healthcare demand and clinical viability. A solar project should be evaluated on its power purchase agreement, grid connectivity and financial structure. A manufacturing facility should be evaluated on supply chains, productivity and market access.
Not on how many political hashtags are trending that afternoon.
Investors need a risk-assessment framework, not a subscription to every international protest livestream.
Reason No. 6: You can invest in a real business without confusing a cryptocurrency experiment with a national economic development programme.
The world of finance is wonderfully inventive. Traditional businesses take years to establish customers, develop products, build distribution and generate cash flows. Some financial experiments, meanwhile, appear to believe that a digital token, a celebrity association and a sufficiently ambitious presentation can accomplish much the same thing before the next quarterly review.
And when the proposed investment destination happens to be a market with substantial geopolitical, financial and regulatory uncertainty, the imagination becomes even more impressive.
Perhaps the next investment presentation will simply replace the financial projections with a QR code and a promise that the future is decentralised.
Unfortunately, banks still ask questions. Auditors still examine accounts. Regulators still have rules. And investors still prefer to know where their money is going.
A company’s valuation should be supported by cash flows, governance, credible business fundamentals and a viable commercial model—not merely by a fashionable digital token, a celebrity endorsement or someone’s extraordinary confidence in their own financial invention.
Innovation deserves capital. Financial theatre deserves due diligence.
Reason No. 7: Foreign investors sometimes leave. Sometimes they return. Apparently, even capital occasionally needs a little space.
After months of foreign equity outflows, overseas investors returned strongly to Indian equities in November 2026.
As the old saying goes: if someone leaves in the morning and returns by evening, perhaps the relationship was never over. Perhaps the valuation discussion simply needed another meeting. Or perhaps someone finally checked the fundamentals after spending too much time listening to the noise.
We would not recommend applying this relationship theory to every investment committee, but it makes an interesting observation about the mobility of global capital.
The serious point is that foreign investors respond to earnings, valuations, liquidity, currency movements, geopolitical risks, interest rates and alternative opportunities.
Their return should not be treated as a permanent endorsement, just as their departure should not be mistaken for a permanent rejection.
India must continuously earn investor confidence through policy credibility, institutional strength, commercial execution and sustainable returns.
Capital is not sentimental. It does not promise to stay because you made a compelling speech. It stays when the numbers make sense.
And that brings us to the real reasons to invest.
2. INDIA: NOT JUST A MARKET, BUT AN ECONOMIC PLATFORM
India’s investment proposition begins with something difficult to manufacture through advertising: scale.
The United Nations’ 2026 population estimate places India’s population at approximately 1.477 billion. That represents an enormous potential consumer base, workforce, entrepreneurial ecosystem and domestic demand market.
But population alone is not an investment thesis. Purchasing power, income distribution, urbanisation, household formation, access to finance, consumption patterns and productivity determine how much of that population becomes commercially addressable.
India’s economic trajectory is nevertheless significant. The Reserve Bank of India’s September 2026 professional forecasters’ survey placed median real GDP growth expectations at 7.1% for FY2026–27 and 7.0% for FY2027–28.
For international investors, the opportunity is not simply to participate in economic expansion. It is to identify the businesses and infrastructure systems that enable that expansion.
India offers several interconnected investment advantages:
- A large and increasingly diverse domestic consumer market.
- A substantial workforce across technical, professional, industrial and service occupations.
- Competitive operating costs in many cities and industrial locations.
- Expanding physical and digital infrastructure.
- A growing network of domestic suppliers, entrepreneurs and specialist service providers.
- Government programmes supporting manufacturing, renewable energy, healthcare, entrepreneurship and infrastructure.
- Opportunities to establish domestic operations and develop export-oriented capabilities.
- A large English-speaking professional community and established international business connections.
The strategic opportunity is to combine international capital, technology, management expertise and market access with India’s productive capacity.
The most compelling investment is not necessarily the business that sells more products in India. It may be the business that builds more capability in India.
3. SIX INVESTMENT OPPORTUNITIES THAT DESERVE SERIOUS ATTENTION
3.1 Hospitals and medical colleges: Investing in an essential economic sector
If there is one sector where India’s population, income growth, urbanisation and infrastructure requirements converge, it is healthcare.
Healthcare investment is not simply a commercial opportunity. It is an opportunity to build essential national capacity while developing sustainable businesses.
Demand extends across:
- Multispecialty and tertiary-care hospitals.
- Secondary-care hospitals in emerging cities.
- Medical colleges and teaching hospitals.
- Cancer, cardiac, neurological and orthopaedic centres.
- Diagnostic laboratories and imaging networks.
- Day-care surgery and specialised outpatient facilities.
- Rehabilitation, elderly care and home healthcare.
- Medical technology, hospital equipment and healthcare IT.
- Healthcare supply chains, pharmaceuticals and medical devices.
India has expanded its medical education infrastructure considerably. Government figures published in August 2026 reported 846 medical colleges, approximately 139,864 MBBS seats and 86,360 postgraduate medical seats.
That expansion is substantial, but it does not eliminate the need for investment in clinical capacity, faculty, training quality, technology, research and regional healthcare accessibility.
The opportunity is particularly relevant in Tier-II and Tier-III cities, where investors may identify underserved catchments, lower land costs and opportunities to develop regional healthcare networks.
However, hospital investment must be evaluated through operational fundamentals rather than population statistics.
Critical investment metrics:
- Capital expenditure per operational bed.
- Bed occupancy and patient throughput.
- Average revenue per occupied bed.
- Revenue mix across specialities and payer categories.
- Doctor recruitment and retention costs.
- EBITDA margin and operating leverage.
- Working-capital requirements and receivable cycles.
- Debt-service coverage ratio (DSCR).
- Break-even occupancy and payback period.
- Accreditation, regulatory compliance and clinical governance.
Medical colleges require an additional layer of diligence: land and infrastructure requirements, regulatory permissions, faculty availability, teaching-hospital capacity, clinical case volumes and long-term operating costs.
A medical college cannot be treated as a real-estate development with classrooms attached. Its economic viability depends on the quality and scale of its academic and clinical ecosystem.
The opportunity: International hospital operators, healthcare investors, medical education groups, medical technology companies and infrastructure funds can explore greenfield development, joint ventures, management contracts, technology partnerships and acquisitions.
India does not merely need more hospital buildings. It needs stronger healthcare institutions.
3.2 Solar and renewable energy: Turning sunshine into industrial advantage
India’s renewable-energy opportunity is moving beyond electricity generation.
The next investment cycle will increasingly involve energy storage, grid integration, transmission, hybrid generation, industrial decarbonisation, distributed energy and green industrial infrastructure.
As of 30 September 2026, India’s installed solar power capacity had reached approximately 171.05 GW. Total installed renewable capacity, excluding large hydro, stood at approximately 247.18 GW.
This is a substantial industrial and investment ecosystem.
Opportunities extend across:
- Utility-scale solar parks.
- Commercial and industrial rooftop solar.
- Solar EPC and project development.
- High-efficiency photovoltaic manufacturing.
- Battery energy storage systems.
- Solar-plus-storage and hybrid projects.
- Transmission and grid infrastructure.
- Operations and maintenance.
- Energy management software and forecasting.
- Green hydrogen and associated industrial supply chains.
- Distributed solar for businesses, institutions and rural applications.
The business opportunity is not restricted to large infrastructure developers. Medium-sized investors can participate through EPC businesses, equipment distribution, industrial rooftops, energy services, component manufacturing and project-level partnerships.
Government programmes supporting renewable-energy deployment and domestic manufacturing can improve investment economics, subject to eligibility and applicable conditions.
However, sunshine is not a substitute for financial modelling.
Critical investment metrics:
- Capital expenditure per MW.
- Power purchase agreement tariff and duration.
- Offtaker creditworthiness.
- Capacity utilisation factor.
- Module efficiency and degradation.
- Land acquisition and evacuation costs.
- Grid connectivity and transmission availability.
- Financing cost and DSCR.
- Storage economics and balancing requirements.
- O&M expenditure and equipment warranties.
- Merchant-market exposure and regulatory risk.
A project with excellent solar irradiation but weak evacuation infrastructure or an unreliable offtaker can become an expensive demonstration of why technical potential and commercial viability are not the same thing.
The opportunity: India can become a platform not only for renewable-energy generation, but also for the manufacturing, financing, storage and industrial utilisation of clean energy.
3.3 Hospitality: India’s next opportunity is not just more hotel rooms
India’s hospitality sector benefits from domestic leisure travel, business travel, weddings, meetings and conferences, pilgrimage tourism, medical tourism and international visitors.
The opportunity is particularly attractive because hospitality investment can be structured across multiple capital and operating models.
These include:
- Luxury and premium hotels.
- Mid-market and business hotels.
- Boutique and lifestyle properties.
- Resorts and destination hospitality.
- Serviced apartments.
- Budget and economy hotels.
- Convention and MICE infrastructure.
- Wellness and medical tourism facilities.
- Heritage and experiential accommodation.
- Hotel management and franchise businesses.
Industry estimates published in October 2026 placed premium hotel occupancy at approximately 75–77% for that month, with average room rates around ₹8,700–₹8,900. Industry revenue growth for FY2026–27 was projected at 7–9%.
These figures are encouraging, but they should not be mistaken for guaranteed performance across every city, property category or investment location.
The opportunity may be particularly interesting in emerging business destinations, industrial corridors, religious tourism circuits, medical hubs and cities where branded accommodation remains relatively underdeveloped.
Critical investment metrics:
- Average daily rate (ADR).
- Occupancy rate.
- Revenue per available room (RevPAR).
- Gross operating profit per available room.
- Construction cost per key.
- Food and beverage revenue contribution.
- Distribution and booking commissions.
- Staff and energy expenditure.
- Seasonality and customer acquisition cost.
- Stabilisation period and debt-service capacity.
Investors should also consider asset-light management contracts, franchising and operating partnerships instead of assuming that owning the property is always the best investment structure.
A hotel does not become profitable simply because its lobby looks impressive on Instagram.
The opportunity: Combine international hospitality standards with local demand, efficient operating models and carefully selected destinations.
3.4 Small and medium-sized startups: Invest in capability, not just valuation
India’s startup ecosystem is no longer confined to a handful of metropolitan technology companies.
It extends into manufacturing, logistics, healthcare, financial technology, artificial intelligence, enterprise software, agriculture, consumer products, education, climate technology and industrial services.
Government figures reported in November 2026 placed the number of DPIIT-recognised startups above 2.62 lakh.
That is a remarkable expansion of entrepreneurial activity. It is not, however, a count of profitable businesses or a guarantee of investment quality.
For international investors, some of the most attractive opportunities may exist in smaller businesses that have already demonstrated customer demand but need capital, technology, professional management, distribution or international market access.
Potential investment and collaboration models include:
- Minority equity investment.
- Strategic joint ventures.
- Technology licensing.
- Distribution partnerships.
- Contract manufacturing.
- Co-development agreements.
- Acquisition of specialist capabilities.
- International franchising.
- Export partnerships.
- Corporate venture investment.
A smaller Indian company may have a technically strong product, a loyal domestic customer base or an established regional distribution network. What it may lack is access to international procurement systems, institutional finance, global quality certifications or professional expansion strategy.
That gap can become an investment opportunity.
Critical investment metrics:
- Revenue quality and customer concentration.
- Gross margin and contribution margin.
- Customer acquisition cost and lifetime value.
- Working-capital cycle.
- Recurring revenue and retention.
- Intellectual property ownership.
- Promoter governance and financial transparency.
- Cash burn and funding runway.
- Scalability without disproportionate capital expenditure.
- Export readiness and regulatory compliance.
The objective should not be to invest in the largest number of startups. It should be to identify businesses capable of becoming stronger, more competitive and more valuable enterprises.
3.5 Indian regional food chains: Taking local brands to international markets
Here is an opportunity that deserves far more international attention.
India has thousands of regional food businesses, restaurant chains, speciality kitchens, snack brands, traditional food manufacturers, dessert businesses and emerging QSR concepts.
Many have already developed something that cannot be manufactured through a marketing campaign: customer loyalty and a distinctive product identity.
Yet a considerable number remain geographically concentrated, professionally underdeveloped or unable to access international distribution.
This creates an opportunity for international food companies, hospitality groups, private investors, franchise operators and strategic distributors.
Imagine a successful regional Indian food chain entering the Gulf, Southeast Asia, Europe or North America through a structured international partnership.
The opportunity could include:
- Master franchising.
- International joint ventures.
- Brand licensing.
- Overseas restaurant development.
- Centralised production and distribution.
- Frozen and packaged food exports.
- Private-label manufacturing.
- Cloud-kitchen partnerships.
- International retail distribution.
- Strategic investment in scalable regional brands.
India’s food-services market was estimated at approximately US$90 billion in 2025–26, with projections placing it near US$150 billion by 2030. Organised food-service businesses are expanding faster than the fragmented unorganised segment.
But the real opportunity is not simply to open more restaurants.
It is to develop brands with repeatable products, standardised processes, consistent quality, strong procurement and sustainable unit economics.
Critical investment metrics:
- Average order value.
- Same-store sales growth.
- Food cost and wastage.
- Outlet-level EBITDA.
- Franchisee economics.
- Customer repeat frequency.
- Supply-chain reliability.
- Brand recognition and customer retention.
- Product shelf life and export compliance.
- International logistics and cold-chain costs.
A successful regional food business should not have to remain a local secret forever.
India has food brands that could travel internationally. What many need is not another food blogger reviewing the menu, but a serious distribution partner, professional capital and a credible global expansion strategy.
3.6 Retail and consumer startups: Build the next generation of Indian brands
India’s consumer market is evolving rapidly.
Digital payments, e-commerce, social commerce, organised retail, changing household preferences and growing demand for differentiated products are creating opportunities for both Indian entrepreneurs and international businesses.
India’s online retail market was projected to exceed US$90 billion in 2026, with estimated growth of approximately 22–24%.
The opportunity spans:
- Beauty and personal care.
- Fashion and lifestyle.
- Health and wellness products.
- Consumer electronics.
- Home and furniture.
- Food and beverage brands.
- Premium and affordable luxury.
- Household products.
- Sustainable consumer goods.
- Direct-to-consumer businesses.
- Omnichannel retail.
- Digital-first brands with physical distribution.
International businesses can enter through local subsidiaries where permitted, joint ventures, distribution partnerships, licensing, franchise structures, acquisitions or strategic investments.
The most important consideration is localisation.
A product that succeeds in one international market may not automatically succeed in India. Pricing, packaging, product specifications, distribution, customer service and marketing must reflect local purchasing behaviour.
Critical investment metrics:
- Customer acquisition cost.
- Customer lifetime value.
- Gross merchandise value versus recognised revenue.
- Gross margin and contribution margin.
- Inventory turnover.
- Return and cancellation rates.
- Repeat purchase rate.
- Distribution cost.
- Marketing efficiency.
- Cash conversion cycle.
The next major consumer brand may emerge from a relatively small business that understands its customers better than a multinational understands its market-entry presentation.
India does not simply need more brands. It needs better products, stronger distribution and businesses that understand the economics of Indian consumers.
4. BEYOND THE SIX: OTHER SECTORS GLOBAL INVESTORS SHOULD NOT IGNORE
A serious India investment strategy should not stop at the most visible sectors.
Several additional areas deserve structured attention:
| Sector | Potential investment opportunities |
|---|---|
| Manufacturing | Electronics, components, engineering, industrial equipment, contract manufacturing |
| Logistics | Warehousing, cold chains, freight technology, multimodal logistics |
| Healthcare technology | Diagnostics, medical devices, hospital software, remote healthcare |
| Education | Skill development, vocational training, professional education, edtech |
| Data centres | Digital infrastructure, cloud facilities, power and cooling systems |
| Electric mobility | Charging infrastructure, components, battery systems, fleet services |
| Agriculture | Food processing, storage, agri-tech, supply-chain modernisation |
| Financial services | Fintech, SME lending, insurance technology, financial infrastructure |
| Water and waste | Treatment, recycling, industrial water management, waste-to-value |
| Real estate | Industrial parks, logistics facilities, commercial assets and specialised developments |
| Aerospace and defence | Components, precision engineering, maintenance and technology partnerships |
| Tourism and wellness | Medical tourism, destination development, wellness and experiential travel |
The strategic logic is straightforward: India’s economic expansion creates demand not only for final products, but also for the infrastructure, technology, services and institutions required to deliver them.
For investors, this means looking beyond the obvious consumer-facing business and examining the supporting economic architecture.
5. WHY INDIA? THE STRUCTURAL ADVANTAGES THAT MATTER TO INVESTORS
The investment proposition becomes more compelling when India’s market scale is combined with its operating environment.
5.1 Population and domestic demand
India’s population creates substantial potential demand across healthcare, housing, food, mobility, education, financial services and consumer products.
However, investors must segment the market by income, geography, age, affordability and purchasing behaviour. A product designed for a metropolitan premium customer cannot automatically be replicated across smaller cities.
5.2 Competitive workforce and operating costs
India offers a large pool of engineers, technicians, doctors, finance professionals, consultants, skilled workers, designers, software specialists and business operators.
In many locations, labour and professional-service costs can be competitive against established international markets.
But the phrase “cheap labour” should not be confused with low-cost productivity.
Investors must evaluate skills, output per employee, training requirements, attrition, statutory benefits, labour compliance and management capability.
The real advantage is the potential to build competitive operating models with access to a large and diverse talent base.
5.3 Competitive real estate and rental markets
Outside the most expensive central business districts and prime retail locations, many Indian cities offer comparatively attractive land, industrial space, office and commercial rental opportunities.
Tier-II and Tier-III cities can provide meaningful cost advantages for suitable business models.
But property costs vary enormously. Prime retail locations, premium offices and established industrial clusters can be expensive. Investors must also evaluate title, zoning, land-use permissions, infrastructure access, utilities and local approvals.
The objective is not to find the cheapest property. It is to secure the right location at a cost that supports the business model.
5.4 Access to professional expertise
India has a substantial ecosystem of chartered accountants, company secretaries, lawyers, engineers, architects, financial analysts, consultants, technology specialists, project managers and industry professionals.
International businesses can access specialist support for company formation, taxation, regulatory compliance, project structuring, financial modelling, recruitment, technology, supply-chain management and market entry.
The availability of professional services at competitive prices can improve the economics of establishing and operating a business.
However, the quality of advice matters more than the lowest professional fee. Investor protection, technical competence and accountability must remain non-negotiable.
5.5 Government policies and investment incentives
India has developed a broad policy architecture to encourage domestic and international investment.
Relevant initiatives include:
- Production Linked Incentive programmes across selected manufacturing sectors.
- Startup India and associated funding and support mechanisms.
- Renewable-energy programmes and manufacturing incentives.
- PM Surya Ghar and other distributed solar initiatives.
- Healthcare infrastructure and medical education expansion programmes.
- Infrastructure development and industrial-corridor initiatives.
- Digital public infrastructure and financial inclusion programmes.
- MSME financing and credit-support mechanisms.
- State-level industrial policies, investment subsidies and sector-specific incentives.
India permits up to 100% foreign investment under the automatic route in many sectors, although sector-specific conditions, exceptions and applicable laws must be examined.
For example, foreign investment is permitted up to 100% under the automatic route in specified healthcare and hotel-related activities, subject to applicable policy and regulatory requirements.
Investors should never assume that an incentive announced in a policy document automatically becomes an entitlement. Eligibility, location, investment thresholds, approval requirements, timelines and compliance conditions must be verified before incorporating incentives into financial projections.
5.6 Infrastructure and digital connectivity
Roads, airports, ports, freight networks, industrial corridors, power infrastructure, telecommunications and digital payment systems are changing the operating environment.
India’s digital infrastructure also offers businesses the ability to reach customers, receive payments, distribute services and manage transactions at scale.
For international investors, these developments can reduce certain market-entry and operating barriers, although infrastructure quality remains uneven across locations.
5.7 A business environment with international connections
India offers access to a large domestic market alongside international business relationships, a significant professional diaspora, English-language commercial capabilities and an increasingly sophisticated supplier ecosystem.
For companies seeking to diversify manufacturing, establish service operations, develop regional headquarters or access new consumer markets, this combination deserves serious consideration.
India’s advantage is not that everything is inexpensive. It is that the right combination of market scale, talent, infrastructure, partnerships and operating costs can create a competitive business model.
6. THE NUMBERS THAT DESERVE AN INVESTOR’S ATTENTION
The following indicators provide a useful starting point for evaluating India’s investment proposition.
| Indicator | Latest available position | Investment significance |
|---|---|---|
| India’s population, 2026 | Approximately 1.477 billion | Large potential consumer and workforce base |
| Real GDP growth forecast, FY2026–27 | 7.1% | Strong projected economic expansion |
| Real GDP growth forecast, FY2027–28 | 7.0% | Continued growth expectation |
| Medical colleges | 846 | Expanding medical education infrastructure |
| MBBS seats | Approximately 139,864 | Growing medical training capacity |
| Installed solar capacity, September 2026 | 171.05 GW | Significant renewable-energy ecosystem |
| DPIIT-recognised startups, November 2026 | More than 2.62 lakh | Broad entrepreneurial ecosystem |
| Premium hotel occupancy, FY2026–27 forecast | 72–74% | Supportive hospitality demand outlook |
| Indian food-services market | Approximately US$90 billion | Large organised and unorganised market |
| Food-services market projection, 2030 | Approximately US$150 billion | Potential expansion of organised food businesses |
| Online retail market projection, 2026 | More than US$90 billion | Expanding digital consumer economy |
Figures have different reporting periods and definitions. Forecasts are projections, not guaranteed outcomes. Market-size estimates should not be added together because their scopes may overlap.
7. FOREIGN CAPITAL, DOMESTIC CAPITAL AND THE DIFFERENCE BETWEEN INTEREST AND COMMITMENT
India’s investment story should be assessed through actual capital flows rather than isolated market headlines.
For FY2025–26, reported gross FDI inflows into India were approximately US$94.5 billion. However, gross inflows, investment after repatriation and disinvestment, and net FDI after outward Indian investment are different measures.
This distinction matters.
A country can attract substantial gross investment while also experiencing significant repatriation and outward investment. Neither figure, taken alone, establishes the full strength of its investment environment.
Foreign portfolio investment is different again. Portfolio investors can enter and exit listed markets rapidly in response to valuation, interest rates, global liquidity, currency movements and geopolitical risk.
Strategic foreign direct investment is generally a longer-horizon commitment involving businesses, infrastructure, manufacturing, technology, employment and operating assets.
Investors should therefore distinguish between:
- Foreign portfolio investment.
- Greenfield foreign direct investment.
- Brownfield acquisitions.
- Joint ventures and strategic alliances.
- Private equity and venture capital.
- Domestic institutional and private capital.
A rise in stock-market inflows is not proof that every infrastructure or healthcare project has become more attractive. Equally, a temporary portfolio outflow does not automatically invalidate India’s long-term economic proposition.
Capital does not fall in love with national slogans. It follows credible returns, investable opportunities and confidence in execution.
8. THE RISKS: INDIA IS AN OPPORTUNITY, NOT A GUARANTEED RETURN
A credible investment thesis must acknowledge what can go wrong.
India offers scale and growth potential, but investors must navigate a complex and diverse operating environment.
| Risk area | Potential exposure | Investor response |
|---|---|---|
| Regulatory complexity | Delays, approvals and compliance costs | Sector-specific and state-specific diligence |
| Land and property | Title, zoning and acquisition disputes | Independent legal and technical verification |
| Infrastructure | Power, water, transport and grid constraints | Location and utility due diligence |
| Workforce | Skill gaps, attrition and productivity differences | Training, retention and operating controls |
| Financing | Interest rates and refinancing exposure | Conservative leverage and DSCR testing |
| Currency | Rupee depreciation and foreign-currency liabilities | Hedging and currency-matched financing |
| Demand | Pricing pressure and slower customer adoption | Catchment research and scenario modelling |
| Execution | Construction delays and cost overruns | EPC controls, milestone payments and contingency |
| Governance | Partner disputes and financial opacity | Background checks, audits and contractual safeguards |
| Geopolitics | Trade restrictions, tariffs and supply-chain disruption | Diversification and geopolitical stress testing |
Investors should also test their business models against adverse scenarios rather than relying exclusively on optimistic projections.
A practical project-level stress test could include:
- Construction costs increasing by 10–15%.
- Commercial commencement delayed by six months.
- Revenue or utilisation 10% below the base case.
- Financing costs increasing by 200 basis points.
- Customer receivables extending by 30–60 days.
- A 10% adverse currency movement where foreign-currency exposure exists.
These are illustrative stress assumptions, not predictions of what will happen in India. Each project’s sensitivities must be calculated independently.
The strongest investment is not the one with the most attractive presentation. It is the one that remains financially viable when assumptions become less favourable.
9. HOW INTERNATIONAL INVESTORS SHOULD ENTER INDIA
Entering India should be treated as a structured market-development exercise, not an exercise in enthusiasm.
A disciplined approach should include six stages.
Stage 1: Market intelligence
Identify the target sector, customer segments, competitors, demand gaps, pricing structures and regional opportunities.
Stage 2: Partner identification and due diligence
Evaluate promoters, management teams, financial statements, operational capabilities, legal history, customer relationships and market reputation.
Stage 3: Commercial structuring
Select the appropriate entry model: wholly owned subsidiary, joint venture, strategic alliance, acquisition, franchise, licensing, distribution or technology partnership.
Stage 4: Financial and regulatory feasibility
Develop detailed financial models covering capital expenditure, operating expenditure, working capital, funding structures, taxation, incentives, IRR, NPV, DSCR and exit scenarios.
Stage 5: Execution and localisation
Establish the local operating team, supplier relationships, compliance framework, technology systems and customer acquisition strategy.
Stage 6: Performance governance
Track operational and financial performance through measurable KPIs, reporting systems, independent audits, risk controls and periodic investment reviews.
The correct entry strategy is not necessarily the one that creates the largest initial footprint. It is the one that establishes a sustainable commercial position with the ability to scale.
10. THREE INVESTMENT SCENARIOS FOR THE NEXT FIVE YEARS
Rather than assuming a single growth trajectory, international investors should consider three planning scenarios.
Scenario A: Accelerated expansion
Stronger domestic consumption, infrastructure execution, private investment and global supply-chain diversification create favourable conditions.
Potential beneficiaries include healthcare, renewable energy, hospitality, manufacturing, logistics, consumer businesses and technology services.
Investor response: Scale projects with validated demand, secure strategic partnerships and increase capacity in stages.
Scenario B: Disciplined consolidation
Economic growth continues, but competition, pricing pressure, financing costs and execution challenges limit returns.
Investor response: Prioritise operating efficiency, cash flow, productivity, asset utilisation and selective acquisitions.
Scenario C: External and domestic stress
Geopolitical disruptions, trade barriers, currency volatility, inflation, weak demand or financing constraints affect investment performance.
Investor response: Preserve liquidity, reduce excessive leverage, diversify suppliers, protect working capital and delay expansion where project economics deteriorate.
These scenarios are planning frameworks, not forecasts. Their purpose is to ensure that investment decisions remain commercially defensible under different conditions.
11. THE REAL OPPORTUNITY: DO NOT JUST SELL TO INDIA. BUILD WITH INDIA.
There is a significant difference between entering a market to capture demand and entering an economy to create productive capacity.
A foreign healthcare company can establish a hospital. But it can also develop medical education, clinical research, specialist training and regional healthcare networks.
A renewable-energy investor can build a solar project. But it can also establish component manufacturing, energy storage, grid-management capabilities and industrial energy partnerships.
An international food company can sell products in India. But it can also invest in regional Indian brands and take those brands into international markets.
A global retail business can establish stores. But it can also build Indian sourcing networks, develop domestic suppliers and create internationally competitive consumer products.
These are fundamentally different investment propositions.
The first captures market opportunity.
The second builds economic capability.
The third can create a platform for long-term commercial influence.
The next international success story from India may not be a multinational company entering the Indian market. It may be an Indian business, supported by international capital and expertise, entering the world market.
That is where the opportunity becomes particularly interesting.
12. THE iBLUU PERSPECTIVE: CONNECTING GLOBAL CAPITAL WITH INDIAN CAPABILITY
The analytical perspective of J Parasher, Founder and Managing Director of iBluu Consulting Venture (iBCV), a venture of iBluu Corporations, focuses on national capability building, global industrial benchmarking and long-horizon economic transformation.
His perspective reframes consulting not as a sectoral play, but as a strategic economic system with export potential, innovation leverage and geopolitical relevance.
For iBluu, the investment opportunity in India is not simply a question of identifying a growing sector. It is about understanding how capital, infrastructure, technology, institutions, enterprise and international partnerships can reinforce one another.
The objective is to help businesses and investors identify commercially viable opportunities, evaluate strategic partnerships, structure investments, navigate market-entry requirements and develop long-term business capabilities.
This means looking beyond the announcement of an investment to the actual architecture of its execution.
Because the difference between an investment announcement and a successful investment is not the size of the headline.
It is the quality of the business model, the discipline of capital deployment and the ability to deliver sustainable results.
13. THE FINAL WORD: THE WORLD CAN KEEP THE DRAMA. INVESTORS HAVE BUSINESSES TO BUILD.
Let the world continue debating international relationships, prestigious awards, viral videos, political egos and geopolitical controversies.
There will always be another headline, another controversy, another award ceremony and another person explaining why the global economy is about to collapse.
But businesses cannot be built on headlines.
Hospitals need doctors. Medical colleges need faculty. Solar projects need financing and grid connectivity. Hotels need customers. Startups need capital and markets. Food brands need distribution. Retailers need customers. Manufacturers need technology, productivity and supply chains.
These are not glamorous challenges. They are considerably more important.
India is not without its problems. It has regulatory complexities, infrastructure gaps, regional disparities, execution risks and intense competition. Investors must understand these realities rather than romanticise the market.
But it also has scale, entrepreneurial energy, expanding infrastructure, a large professional workforce, evolving consumer demand and opportunities across sectors that are essential to the next generation of economic development.
The question for international capital is therefore not whether India is perfect.
The question is whether investors can identify the right opportunities, structure them intelligently and execute them better than their competitors.
Because while some are busy trying to make history on social media, others have the opportunity to build businesses that may still matter twenty years from now.
And perhaps that is the most sensible investment strategy in an increasingly entertaining world.
THE WORLD MAY BE BUSY MAKING DRAMA. INDIA IS BUSY BUILDING AN ECONOMY.
The opportunity is there. The capital, partnerships, expertise and execution must follow.
ABOUT iBLUU CORPORATIONS
iBluu Corporations is a strategic consulting and advisory organisation focused on investment advisory, strategic consulting, infrastructure structuring, business alliances, cross-border partnerships, government engagement, IT advisory and mergers and acquisitions.
Through its advisory approach, iBluu seeks to connect investment opportunities with commercial strategy, institutional capability and long-term economic value creation.
LinkedIn: https://www.linkedin.com/company/ibluu
Website: https://www.ibluu.com/
DISCLAIMER: This article is intended for general informational, strategic and investment-discussion purposes only. It does not constitute investment advice, a securities recommendation, an offer, a solicitation or a guarantee of commercial returns.
Market statistics, industry estimates and forecasts reflect the reporting periods and definitions indicated and may be revised. Projections are not guarantees of future performance. Actual investment outcomes depend on project feasibility, market conditions, regulatory requirements, financing structures, execution capabilities and other commercial factors.
All prospective investors should undertake independent financial, legal, technical, regulatory, tax and commercial due diligence before making investment decisions. Government policies, incentives and foreign investment rules are subject to applicable eligibility conditions and amendments.